

Turn Hail Damage Confusion Into a Clear Game Plan
Hail can pound your roof for only a few minutes yet leave damage that lasts for years. In the Midwest and Plains, late summer and fall storms often hit hard, then move on before anyone has time to check for bruised shingles, dented vents, or cracked siding. From the ground, the roof may look fine, while slow leaks start inside where you cannot see them.
When that happens, roof insurance claims can feel like a second storm. There are new words like ACV, RCV, and depreciation, strict filing timelines, and back-and-forth with adjusters. It is easy to worry about saying the wrong thing or missing a deadline that costs you money.
Our goal with this playbook is simple: walk you step by step from the first inspection after hail hits, all the way to the final depreciation release. When you understand what happens at each stage, you can protect your home, avoid costly missteps, and feel in control of the process. At ACT Roofing and Restoration, a family-owned company established in 1992, we have been helping families through hail and wind damage for decades. Our approach is built on clear communication, free inspections, and customer-first, budget-conscious project management.
Start Strong with a Free, Expert Hail Damage Inspection
After a storm, the clock starts ticking. Even small hail can bruise shingles, loosen granules, and weaken protective layers. That damage may not leak right away, but as temperatures change and snow or rain returns, those weak spots can turn into active leaks, mold, or interior stains. Insurance policies also have limits on how long you have to file a claim after a storm date, so waiting too long can close the window for coverage.
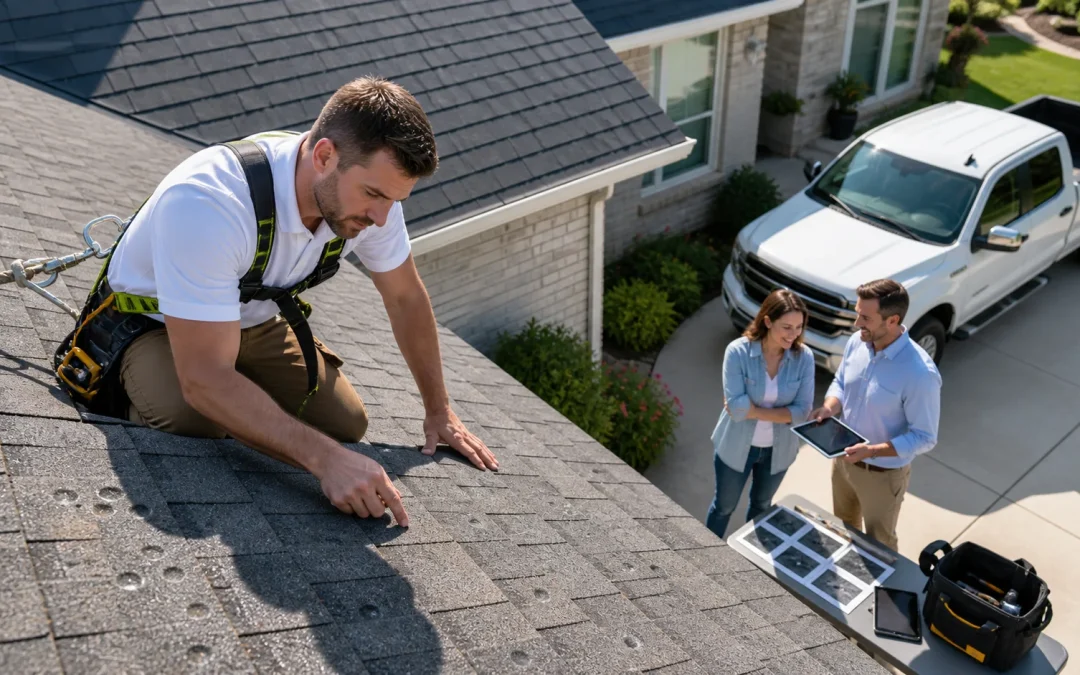
A professional inspection should be safe, thorough, and documented. When we inspect a home, we:
- Access the roof safely instead of guessing from the ground
- Look for hail bruises, cracks, missing granules, and lifted shingles
- Check metal vents, flashings, and gutters for dents and impact marks
- Inspect siding, windows, frames, and screens for chips, fractures, and pitting
All of this matters because your roof is only one part of the storm story. Damage to windows and siding often supports the overall claim and helps show the full force of the hail or wind. Many homeowners are surprised by how much is found only when someone is on the roof, taking close-up photos of damage that is not visible from the ground.
We believe you should be able to make a claim decision based on real evidence, not pressure. That is why we offer free, no-obligation inspections and clear photo reports. Homeowners often tell us they appreciate:
- Straightforward explanations in plain language
- Honest answers about whether damage is likely to meet claim thresholds
- A family-style, customer-oriented approach that feels more like a guide than a salesperson
Filing Roof Insurance Claims with Confidence
Once you know what the storm actually did to your home, the next step is turning that inspection into a strong claim. The photos, measurements, and notes from the inspection connect your roof, window, and siding damage to a specific storm date. That connection is what your insurance company looks for when they review roof insurance claims.
We also help you understand a few key parts of your policy before you file:
- Your deductible, which you are responsible for paying
- Coverage limits for roof, siding, and windows
- Whether your policy is ACV (Actual Cash Value) or RCV (Replacement Cost Value)
To file, you usually call your insurance carrier, share that you have hail or wind damage, and provide the date of loss. They create a claim number and schedule an adjuster visit. When possible, we meet the adjuster at your property so we can point out each area of damage, answer technical questions, and help ensure nothing important is missed. Many homeowners feel this support makes the approval process smoother and are impressed by how efficiently we coordinate with their insurance companies.
After the adjuster visit, your carrier prepares an estimate. For ACV, they start with the cost to replace the roof or other items, then subtract depreciation for age and normal wear. Your first check is often this ACV amount, minus your deductible. We go line by line through that estimate to check that:
- All damaged items from the inspection are included
- The material quality reflects what your home needs
- Quantities and codes match what it will actually take to restore your home
Our customers often tell us they value having a team that handles these details professionally and keeps them informed at each step.
From Scope to Build Day: Managing the Restoration Work
Once the insurance estimate is set, it is time to turn numbers on paper into a real scope of work. We translate the carrier’s estimate into a clear plan for your roof, and when included, your windows and siding. This includes shingle type, underlayment, ventilation, flashing, and any approved accessories. We focus on top-quality materials designed to handle future storms and provide long-lasting performance, not just patch the last one.
Planning a storm restoration project can feel like a lot, so our project managers coordinate the moving parts. That typically includes:
- Permits and any required local inspections
- HOA approvals when needed
- Material orders and deliveries
- Crew scheduling based on weather and your calendar
Most roofs are finished in one or two days, weather permitting. We work hard to keep the project within the approved claim amount and on schedule, so your main out-of-pocket cost is your deductible and any upgrades you choose.
On build day, we follow thorough installation practices. Crews remove old roofing, check the decking underneath, and install ice and water shield in key areas, which is especially important before cold and snow return. We address ventilation and flashing details carefully so the new system sheds water the way it should. After work is complete, we perform a full clean-up, including magnets for nails, then walk the property with you to:
- Confirm materials match what was agreed
- Answer questions about what was done and how to care for it
- Make sure you are satisfied with the results before we move to final paperwork
Homeowners frequently remark that the process is well-organized, completed on time, and that the finished roof, siding, and windows meet or exceed their expectations.
Final Invoices, Depreciation Release, and RCV Payout
The last step in many roof insurance claims is releasing the recoverable depreciation. With ACV coverage, you receive a reduced payment that reflects age and wear, then the process ends there. With RCV coverage, you are eligible for the full replacement cost, but the carrier usually holds back depreciation until the work is finished.
Here is how that works in practice:
- The carrier issues the first ACV check, minus your deductible
- We complete the approved work on your home
- We send a final invoice that matches or supports the carrier’s scope
Once the insurance company receives proof that the repairs are complete, they review the final invoice and release the recoverable depreciation if your policy includes it. We help by sending completion photos and any documents they request, then tracking the status so you are not stuck making repeated calls or trying to decode policy language on your own.
In the end, the financial picture usually looks like this: you pay your deductible and any chosen upgrades, and the insurance payments cover the approved storm damage repairs. You are left with a properly documented, fully restored roof, siding, and windows, ready for the next season, backed by our workmanship standards and available warranties. Many customers describe this as a seamless, well-managed experience from start to finish.
Secure Your Hail Claim Outcome Before the Next Storm
Hail and wind damage do not fix themselves. Small issues grow with time, and the longer they sit, the harder it can be to prove what a single storm actually did. Claim deadlines also do not wait, which is why moving quickly, even if you are not sure about filing yet, is so important.
Starting with a free, no-obligation inspection gives you clear information about your roof, siding, and windows, including damage that may not be visible from the ground, along with a simple explanation of your ACV or RCV options. At ACT Roofing and Restoration, our family-owned team has spent decades helping homeowners turn storm damage into an organized, step-by-step plan that leads from first inspection to final depreciation release. Our storm damage restoration expertise, customer-oriented service, and commitment to quality materials and long-lasting results help protect your home and your budget.
When the next storm rolls through the Midwest or Plains, having that plan in place and a trusted partner to guide you through the insurance claim and repair process can make all the difference for your home and your peace of mind.
Protect Your Home With Expert Roof Insurance Guidance
If you are unsure where to start with storm damage or policy details, we can walk you through every step of your roof insurance claims process. At Act Roofing & Restoration, we document damage clearly, communicate with your adjuster, and help you pursue the coverage you deserve. Reach out today so we can review your situation, explain your options, and schedule an inspection. If you are ready to move forward now, simply contact us to get help.